 Untilfree
Coast FIRE Calculator: When Can You Stop Saving for Retirement?
Coast FIRE is the point where the money you already have invested could grow, on its own, into enough for retirement. You still work to pay today’s bills, but you no longer need to save for later.
What "coasting" means
Normal financial independence means your savings could pay your bills today. Coast FIRE is earlier and gentler: your savings are big enough that, left alone to grow until a traditional retirement age, they would reach your full FIRE number. From then on your job only has to cover what you spend now. You can take a lower-paid job you enjoy, work fewer hours, or simply stop worrying about retirement saving.
What decides it
- Your age now and your target age. The more years your money has to grow, the less you need today.
- Your retirement spending. It sets the full FIRE number you are growing toward.
- Growth after inflation. Coast plans are very sensitive to this. A slightly lower return can change the picture a lot.
Alex is 30 with $100,000 invested and wants to retire at 65, spending $40,000 a year. With the 4% rule, Alex's full FIRE number is $1 million. At 5% growth a year after inflation, $100,000 left alone would grow to about $550,000 by 65 — so Alex is not coasting yet. Alex would need a bit over $180,000 invested at 30 to coast. By 40, the bar would be closer to $300,000, because there are fewer years left to grow.
Coast FIRE vs Barista FIRE
They sound alike but answer different questions. Coast FIRE is about retirement: you have saved enough for later, and work covers today. Barista FIRE is about leaving full-time work now: your savings cover part of your spending and a part-time job covers the rest. Many people pass through one on the way to the other.
Is Coast FIRE risky?
It carries real risks worth knowing:
- Returns are not guaranteed. A weak decade early on can leave you short. Using cautious growth rates helps.
- Spending creeps. If your retirement spending grows, your target moves.
- Life changes. Children, health or housing can change the plan. Coasting is a checkpoint, not a finish line.
Many people keep investing a little after they hit Coast FIRE, as insurance, and to keep the option of full independence earlier.
Should I include a state pension?
Some people do, because a pension later in life lowers what savings must cover. Others leave it out to stay cautious, since rules and ages change. If you include it, use only what you are fairly sure to get.
Questions people ask
What does Coast FIRE mean?
It means your current investments could grow into a full retirement fund by your target retirement age without any more contributions. You still need to earn enough to cover your spending until then.
What return rate should I use for Coast FIRE?
Use a growth rate after inflation and lean cautious. Many planners use around 5% for a broad stock-heavy portfolio and test a lower rate like 3% to see how fragile the plan is.
What is the difference between Coast FIRE and Barista FIRE?
Coast FIRE: saved enough for retirement, still working to cover today. Barista FIRE: already living partly off savings, with part-time work covering the rest.
Can couples do Coast FIRE together?
Yes. Combine your investments and plan around your shared spending in retirement. Ages and retirement dates may differ, so many couples plan around the younger partner.
Does the Untilfree app calculate Coast FIRE?
No. The quick estimate on this page gives a rough Coast FIRE number, but the Untilfree app counts down to full financial independence — the day your savings could cover all your spending. It does not calculate Coast FIRE.
Count down to the day you could stop altogether
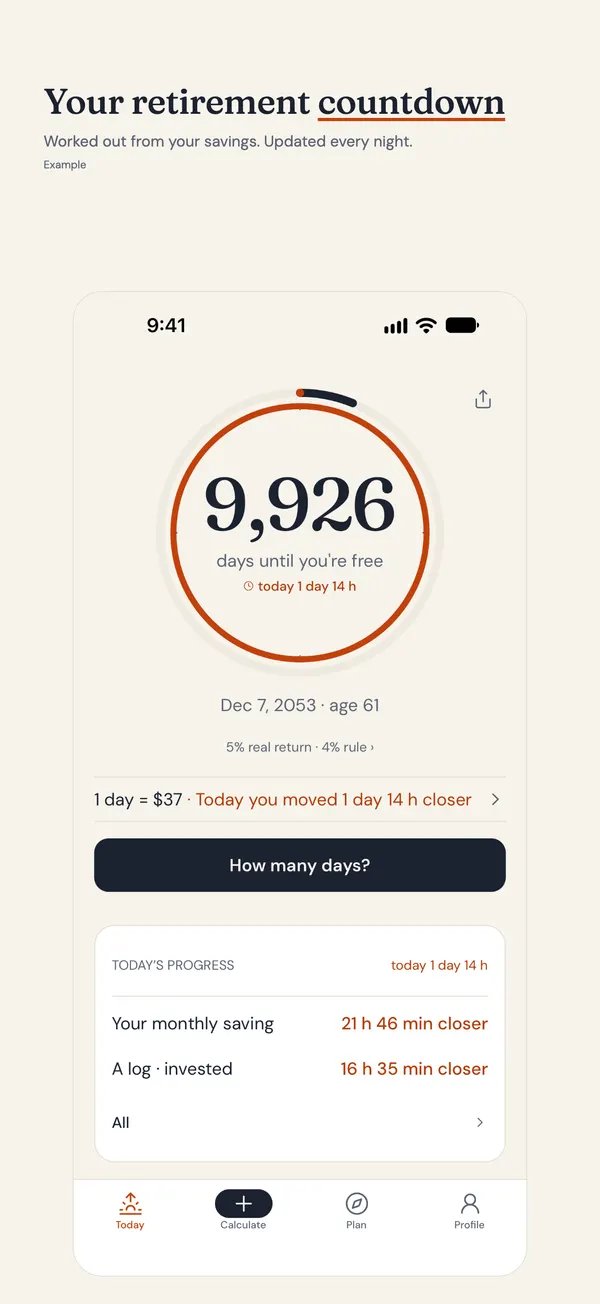
Four questions — your age, savings, monthly investing and monthly spending — and Untilfree gives you a date. Untilfree then counts down every night to the day your savings could pay all your bills.
- Your full freedom day and how many days are left
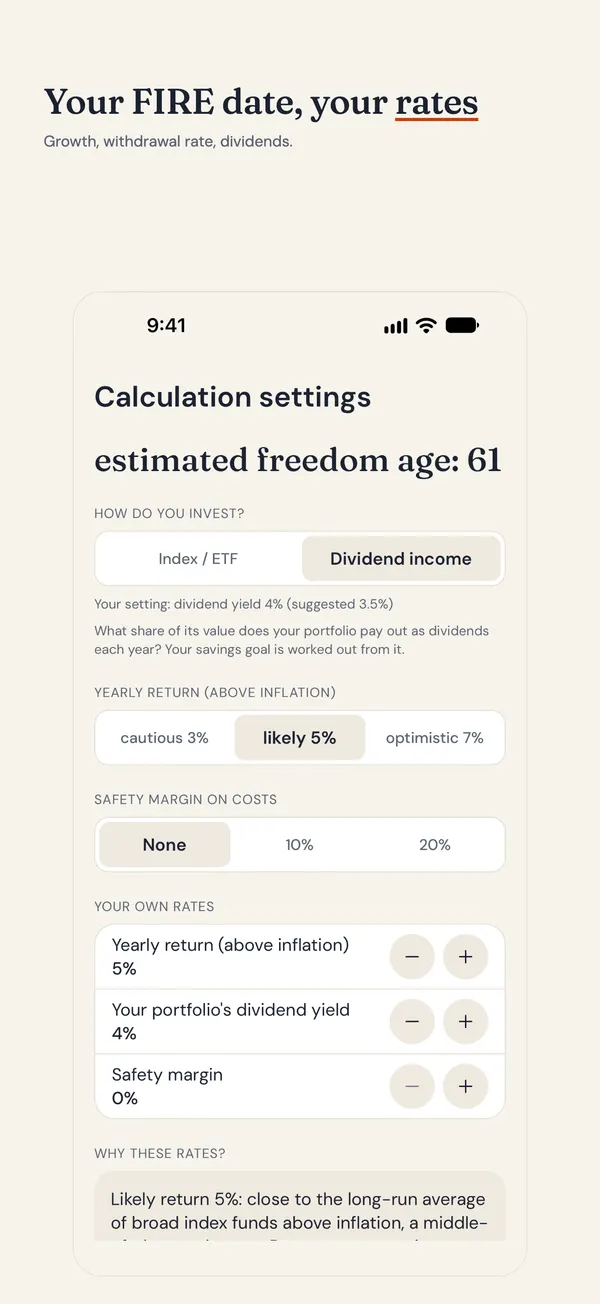
- Cautious, likely and optimistic dates
- See how a raise or a cut moves the date
App Store · Free · Ads, optional Plus · No account · No bank link
Untilfree gives estimates in today’s money (after inflation). Taxes and state pensions are not included. This page is general information, not investment advice.
Published · by Srofia